A clear, evidence-led method for turning an import estimate into actual unit cost through document matching, allocation, and variance review.
Landed cost is a record of the whole journey
A supplier’s unit price is only the first line of an import decision. The goods may still need export packing, domestic transport in China, consolidation, international freight, insurance, customs work, destination handling, local delivery, inspection, bank services, and correction of shortages or damage. Landed cost brings the costs that belong to one shipment into a single, reviewable record and then assigns them to the units you can actually sell or use.
The useful question is not “What percentage should I add to the factory price?” It is “From which starting point to which destination, for which product revision and quantity, are we measuring cost?” A percentage copied from another shipment hides the route, Incoterm, product, customs treatment, exchange dates, and exceptional charges. A versioned ledger keeps those assumptions visible.
This guide focuses on control after the first estimate: how to build a cost baseline, attach evidence to each line, replace estimates with actual invoices, explain variances, and close the shipment with a dependable unit cost. The wider China purchasing and import guides connect this task to supplier, document, and freight decisions; if the full sequence is still unclear, begin with how to start importing from China. The import cost calculator can support an early scenario, while this guide explains how the real order is controlled.
Start by defining the costing boundary
Write the start and end of the calculation in one sentence. A practical boundary might be “from the supplier’s factory in Ningbo to receipt at our warehouse, ready for sale.” Another business may stop at customs release or include delivery to several branches. Both can be reasonable, but their totals are not comparable. If the boundary is vague, people will add some costs twice and leave others outside the file.
Define the unit as carefully as the route. Is the result needed per piece, carton, kilogram, set, or sellable kit? If ten units are used for testing, two are damaged, and eight are supplied as free spare parts, dividing the shipment total by the ordered quantity overstates the number of usable units. Record ordered, shipped, received, accepted, and sellable quantities separately.
Separate three views. The cash view shows when money leaves the business. The customs view supports the legally required declaration in the destination. The management view shows what the business considers part of the product’s economic cost. They overlap, but they are not identical. A refundable tax, a financing charge, or an annual compliance fee may be treated differently in each view. Agree the management policy with the person responsible for accounting and tax.
Give the shipment a stable key, such as purchase-order number plus shipment sequence. Use that key on the cost sheet, invoices, payment records, freight file, customs entry, receiving report, and claim file. The record should still make sense when the buyer who managed the order is away. That simple discipline prevents a late port invoice or inspection charge from being booked against the wrong order.
Build a baseline before approving the order
Create the first complete estimate before the commercial commitment, not after the deposit. Call it a baseline and date it. List product value, one-time charges, origin transport, export handling, consolidation, international freight, insurance, customs-related amounts, destination handling, local delivery, inspection, testing, payment charges, and a clearly identified contingency. A blank line is not zero; mark it as confirmed zero, included elsewhere, estimated, quoted, or still unknown.
Every amount needs a basis column. Note the source document, currency, quotation date, validity, quantity, Incoterm and named place, route, transport mode, weight or volume basis, and owner of the next check. If a forwarder has not quoted destination charges, record “pending destination quote” rather than copying a number from an old shipment. The purpose of the baseline is to show uncertainty early enough to act on it.
Keep assumptions beside the total. A sea-freight estimate based on preliminary carton dimensions can move when final packing changes. A duty scenario based on a working HS code can change if classification or product composition changes. A supplier price can change when artwork, material, or quantity is finalized. Make each assumption specific enough that the team knows what event should trigger a revision.
Set an approval rule. For example, procurement may own product and tooling lines, logistics may own freight and destination estimates, customs support may review classification and valuation inputs, and finance may approve the currency basis and total exposure. In a small business one person may hold several roles; the record should still state which question was checked. A signature on the final number is less useful than a short note showing what the approver reviewed.

Read the supplier price as a package of promises
Start with the current purchase-order revision, not a screenshot from an early chat. Reconcile the unit price with quantity, product specification, packaging, accessories, spares, labeling, tooling, sample credits, tests, certificates, and delivery term. Ask the supplier to separate one-time costs from repeatable unit costs. A mold should not silently increase every future unit if it was fully paid in the first order.
The Incoterm and named point tell you which selected tasks and costs the seller and buyer have agreed to handle. ICC explains that the rules address obligations, risk, and certain costs between the parties, but do not replace the sales contract. Use the practical guide to Incoterms for China imports, read the current rule, and name the place or port precisely. “FOB China” leaves too much open; “FOB [named port], Incoterms 2020” is a more reviewable starting point, though the actual contract and transport plan still matter.
Watch for costs hidden by inconsistent boundaries. An EXW offer may exclude loading, export clearance, and origin movement. A delivered offer may include some destination movement but exclude import duties or unloading. A CIF amount includes specified carriage and insurance obligations to the named port, yet risk and destination expenses require separate reading. Do not rank quotations until each one is restated to the same costing boundary.
Record credits as carefully as charges. A tooling refund, sample credit, quantity rebate, warranty credit, or compensation for a shortage changes the economics only when the entitlement and settlement are clear. Link the credit to the document and status: requested, accepted, issued, or received. Promised credits should not reduce the closed cost until there is evidence that they were applied.
Follow the shipment through origin, freight, and destination
Origin costs can include pickup, export packing, palletizing, consolidation, storage, documentation, terminal handling, and export formalities. Which lines apply depends on the route and commercial term. Ask the forwarder to identify start point, end point, charge basis, inclusions, exclusions, validity, and whether an item is an estimate or a pass-through cost. The guide to comparing freight quotations from China shows how to normalize competing offers before choosing one.
International freight should be tied to the booked shipment, not merely the first quote. Record final chargeable weight, volume, container type, route, carrier or service, surcharges, and any change after booking. If the order is split between air and sea, create separate shipment legs and later allocate them to the units carried on each leg. A blended average can hide the real cost of the urgent portion.
At destination, collect the items that are often absent from a supplier or origin quote: terminal or handling charges, document release, customs broker service, inspection, storage, demurrage or detention where applicable, local transport, unloading, and delivery exceptions. Do not assume these are universal names or fixed charges. Ask for the invoice and the event that created it. A fee caused by a document delay should be visible as an exception rather than buried inside normal freight.
Insurance deserves its own line and evidence. Note the insured value basis, route, coverage wording, deductible, policy or certificate, and the shipment it covers. If damage occurs, keep claim-related recoveries separate from the original cost until accepted. Insurance proceeds can affect the management result, but they do not erase the operational cause of the loss.
Customs value and landed cost answer different questions
The World Trade Organization describes transaction value as the primary basis for customs valuation when the required conditions are met: the price actually paid or payable, with specified adjustments. The World Customs Organization likewise explains that other methods follow in a prescribed order when transaction value cannot be used. That legal valuation process is not the same as a company’s landed-cost worksheet.
A management ledger may include items that are outside customs value, while customs law may require an adjustment that was not stated as a supplier invoice line. Treatment of packing, assists, royalties, commissions, freight, and insurance depends on the governing destination rules and the facts. The customs valuation guide for China imports covers that specialist decision and its evidence.
Keep fields for declared customs value, duty base, duty or other border amounts, authority reference, exchange basis, declaration number, and reviewer. Do not make the landed-cost formula calculate customs value by assumption. Feed the confirmed customs result into the management ledger after the qualified check. This separation makes a later customs query easier to answer because commercial costing has not overwritten the legal reasoning.
Destination law also controls whether a tax is recoverable, capitalized, expensed, or treated another way. A buyer should not copy the treatment used in another country or another company. Record the amount and document first, then follow the applicable accounting, tax, and customs advice. The article can explain the workflow; it cannot supply a universal duty or tax rate.
Treat currency and time as part of every cost line
An amount without its currency and date is incomplete. Keep the original amount, original currency, conversion rate, rate source, applicable date, converted amount, and purpose of conversion. The customs declaration may require an official basis that differs from the business’s budgeting or accounting policy. Store both where necessary and label them clearly.
A purchase can involve a deposit rate, a balance-payment rate, a freight-invoice rate, and an accounting recognition rate. Combining them into one convenient average may be useful for a scenario, but it should not replace the actual records. When management wants to see the effect of currency movement, separate price variance from foreign-exchange variance. That prevents a logistics team from being blamed for a market movement it did not control.
Also record time-dependent quote terms. Freight validity, free time, storage, testing, permit validity, and supplier price validity can expire. Add an “as of” date to the baseline and a next-review date to uncertain lines. A clear expiry signal is more useful than a false impression of precision.
If a payment includes several orders, split it using the supporting remittance and supplier statement. If a bank or payment provider takes charges from either side, document the gross amount, fee, net amount, and which order bears it. The supplier-payment milestones guide explains how payment evidence can be linked to order progress without guessing whether one banking route is available for every transaction.
Allocate shared costs using a rule that reflects the driver
A mixed shipment rarely has one perfect allocation method. Product value may be a sensible basis for insurance or an ad valorem charge. Weight may better explain dense inland transport. Volume may be closer to the driver for a light LCL shipment. Units may suit a uniform labeling fee. Customs duties usually need product-specific classification and value rather than a shipment-wide average.
Choose the driver line by line and state it. Do not allocate every shared amount by purchase value because the spreadsheet makes it easy. A low-value bulky product can consume most of the container space, while a small high-value item can carry more insurance exposure. The goal is a consistent, explainable estimate, not mathematical decoration.
Keep directly attributable costs direct. If a laboratory test applies only to one SKU, assign it to that SKU. If urgent air freight moves only replacement parts, do not spread it across unaffected sea-freight goods unless the business has an explicit policy to do so. Shared costs should be pooled only after the direct lines are removed.
Run a reasonableness check after allocation. Compare cost per unit, cost as a share of purchase price, weight, volume, and expected margin across SKUs. A surprising result may be correct, but it should be explainable. Save the allocation version and rule so that a later shipment can be compared on the same basis.
Replace estimates with actual documents as the shipment moves
Use simple statuses: estimated, quoted, committed, invoiced, paid, disputed, credited, and closed. Update the same ledger instead of creating separate spreadsheets for procurement, freight, and finance. Preserve the baseline column so that the original decision remains visible. The actual column should never erase what the team knew when it approved the order.
For each actual cost, match three things: the service or goods ordered, evidence that the event occurred, and the invoice or payment. For a pickup, that may be the approved quote, warehouse receipt, and forwarder invoice. For inspection, it may be the scope, report, and invoice. For a destination fee, it may be the tariff or notice, release event, and paid receipt. A payment alone does not prove the charge belongs to the shipment.
Use the import documents guide to organize the commercial invoice, packing list, transport record, origin evidence, and destination documents. File naming matters: include shipment key, supplier or provider, document type, date, currency, and revision. A clean record reduces time spent reconstructing the shipment when an auditor, partner, or customs adviser asks a question.
Set a closeout window after delivery. Some invoices arrive later, claims remain open, or final local delivery adjustments are pending. Mark the cost as provisional until material lines are received or accrued according to policy. Then lock the closed version and require a documented adjustment if a late invoice changes it.
Explain differences instead of only reporting them
Calculate the difference between baseline and actual for each line, both as an amount and in a useful relative form. Then assign a cause. Common causes include quantity change, specification change, packing dimensions, route change, booking delay, rate expiry, classification update, currency movement, inspection finding, storage event, document error, split shipment, shortage, or an estimate that was simply incomplete.
Separate controllable and external causes with care. A port disruption may be external, but the cost of avoidable storage caused by a late document is a process failure. A currency movement may be external, but leaving an approved quote unbooked until it expired may be controllable. The purpose is learning, not blame. Use evidence and give the owner a chance to explain the sequence.
Set thresholds that trigger review. A small variance may be accepted with a note, while a material change may require the buyer, logistics owner, and finance approver to reopen the business case. Thresholds should reflect the order’s margin and risk rather than a universal percentage. A thin-margin product can be affected by a difference that looks small at shipment level.
Turn repeated causes into new controls. If final carton dimensions repeatedly raise freight cost, require production packing data before booking. If destination charges are often missing, make a complete destination schedule a quote condition. If bank fees are misallocated, change the payment reconciliation template. A good closeout improves the next baseline.

Handle shortages, damage, rework, and free units openly
The denominator can change after dispatch. Record received quantity, accepted quantity, damaged quantity, samples, warranty spares, and items held for investigation. Decide which units are economically available according to an explicit policy. Dividing by the purchase-order quantity can make a damaged shipment look cheaper than it really was.
Keep the original product cost, extra handling, survey, repair, replacement freight, disposal, and claim recovery as separate lines. This lets management see both the cost of obtaining usable goods and the operational loss. If a supplier sends replacements without charge, their freight and handling may still be real costs. If a claim is expected, show it as pending rather than netting it before acceptance.
Quality work belongs in the cost story when it changes usable output or creates a shipment expense. The scope of inspection and quality control should be defined before the event; an inspection invoice should not be confused with the financial effect of defects it discovers. Keep these linked but distinct.
Decide how to treat indirect and financing costs
Some businesses want a narrow landed cost ending at warehouse receipt. Others also examine financing, inventory holding, internal labor, software, compliance programs, storage after receipt, or expected warranty cost. Define a core shipment cost first, then add a separate management view for indirect items. Mixing both without labels makes comparisons between orders unreliable.
Time has an economic effect. A longer route may lower freight but tie up cash and increase stockout risk. Those effects are useful in a mode decision, yet they are not the same as an invoiced freight charge. Keep modeled opportunity costs in a scenario column and actual bank or financing charges in an evidence column. Readers can then see what was paid and what was estimated for decision-making.
When timing and stock risk influence the route, compare air and sea on the same service boundary and business assumptions. The landed-cost closeout can later show whether those assumptions were reasonable, but it should not rewrite the earlier decision with hindsight.
Illustrative example: three products in one consolidated shipment
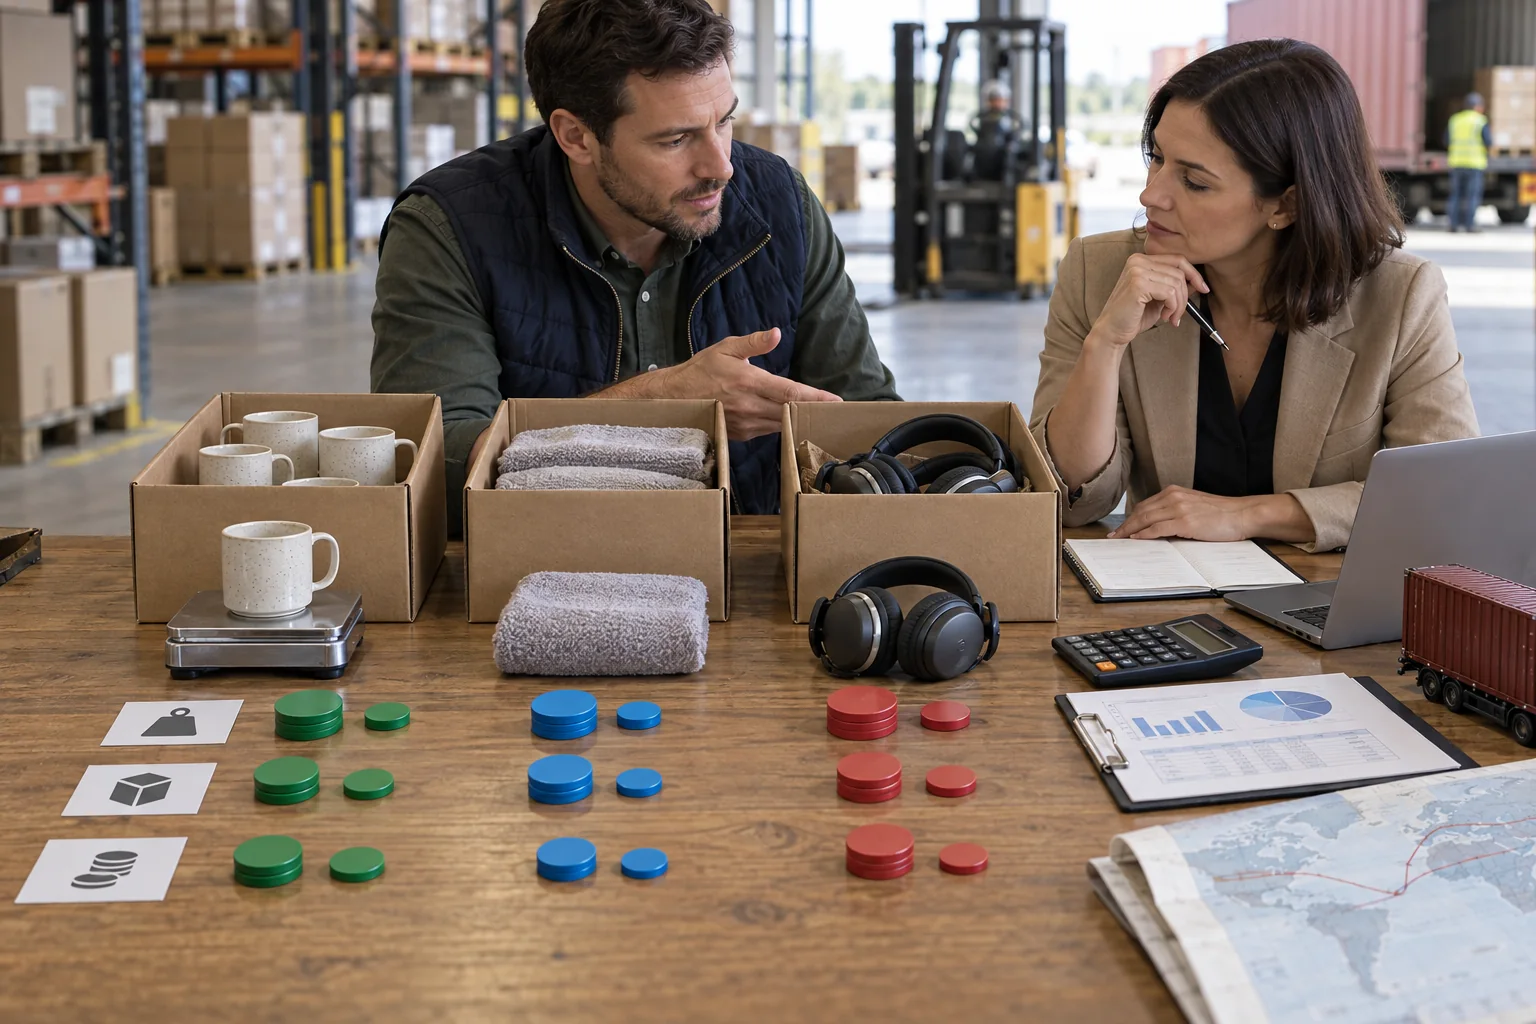
Consider a fictional shipment containing ceramic cups, folded towels, and headphones from three suppliers. The figures in this example are deliberately illustrative and are not current rates, quotations, duties, taxes, or an exchange-rate recommendation. The buyer defines the boundary as receipt of accepted goods at one warehouse and keeps all source amounts in their original currencies.
Product prices and the cup packaging test are direct. China pickup and consolidation are allocated by each supplier’s inbound cartons. International LCL freight and destination handling are allocated mainly by measured volume. Cargo insurance is allocated by insured value. Each product’s customs amount comes from its own confirmed classification, value, and destination treatment rather than a blended percentage.
Before approval, the team marks final packed volume, destination handling, and the customs result as open. The baseline passes only because the business case remains viable under a documented higher-cost scenario. After packing, the towel cartons occupy more space than the supplier estimated. Freight increases for that SKU. The headphones need a late document correction, which creates a small service fee. The cups arrive with one damaged carton.
At closeout, the team replaces every available estimate with an invoice or authority record. It allocates the damaged units according to its usable-unit policy and records the open recovery separately. The variance report shows three different causes: inaccurate packing data, document rework, and physical damage. A single statement that “shipping was more expensive” would have hidden all three actions needed for the next order.
The new baseline requires final carton measurements before freight booking, a document check before dispatch, and stronger packaging evidence for ceramics. The value of the exercise is not the fictional total. It is the link between each variance, its evidence, and a specific control.
Close the shipment with a short, reviewable pack
- The costing boundary, shipment key, product revision, and sellable unit are stated.
- The approved baseline, date, assumptions, and approvers are preserved.
- Every line shows currency, source, status, and allocation method.
- The purchase price matches quantity, specification, packaging, and Incoterm.
- Origin, international, destination, and local-delivery costs are separated.
- Customs value and management landed cost remain distinct records.
- Rates and conversion dates are recorded for their stated purpose.
- Shared costs use documented drivers; direct costs stay with the relevant SKU.
- Actual invoices, receipts, shipment events, and credits are matched.
- Shortage, damage, rework, and recovery remain visible.
- Material variances have a cause, owner, and corrective action.
- The closed unit cost feeds the margin review and next-order baseline.
If customs or destination entries are still uncertain, review the current file with qualified support before treating the number as final. The customs clearance service page explains the information needed to scope an actual case. No article or calculator can confirm a destination-specific liability without the goods, classification, documents, route, and current rules.
Sources and limits used in this guide
The customs distinction is based on the WTO technical explanation of customs valuation and the WCO overview of the Valuation Agreement. They explain transaction value and the sequence of valuation methods; they do not turn a management worksheet into a customs declaration.
The division of selected obligations, risks, and costs comes from the ICC Incoterms 2020 questions and answers. The UK Method 1 guidance is used only as an example of destination-specific treatment, not as a rule for every importer.
The World Bank import-cost methodology illustrates separate process stages, while UNCTAD’s trade and transport cost dataset shows why costs vary by economy, commodity, and mode. No current freight rate, duty, tax, fee, or exchange rate is taken from these sources.
Frequently asked questions
Is landed cost the same as customs value?
No. Customs value is a legal valuation used for customs purposes under destination rules. Landed cost is a management view of the costs assigned to bringing goods to a defined point. Some lines overlap, but the two calculations must remain separately reviewable.
Can I calculate landed cost by adding one percentage to the factory price?
A percentage can support a rough early scenario, but it cannot close a real shipment. Route, product, quantity, packing, Incoterm, customs treatment, destination charges, currency dates, and exceptions must be recorded from the actual order.
Should duties and taxes be allocated by product value?
Do not use a blended allocation before the product-specific legal calculation. Classification, customs value, origin, destination rules, and tax treatment may differ by SKU. Bring the confirmed result into the management ledger afterward.
How should freight be split across several SKUs?
Use the driver that best explains the charge. Volume may suit light LCL cargo, weight may suit dense freight, and direct shipment legs should stay with the goods carried. State the rule and run a reasonableness check.
When is the landed cost final?
Close it after material invoices, customs and receiving evidence, credits, and known claims are recorded or handled under an agreed accrual policy. Lock the version and document any later adjustment.
Where should damage or shortage appear?
Keep the original cost, unusable quantity, extra handling, repair or replacement, and any recovery on separate lines. This shows both the cost of usable goods and the operational loss without assuming a claim will be paid.
Does the cheapest freight quote produce the lowest landed cost?
Not necessarily. Different quotes can use different endpoints, chargeable measures, exclusions, validity, and destination assumptions. Normalize the scope, then compare the total scenario and the operational risk.
Make the final number easy to explain
A dependable landed cost is not a crowded spreadsheet with a precise-looking total. It is a short chain of evidence: what the team expected, what changed, what was paid, how shared costs were assigned, how many usable units arrived, and what should change next time. Someone outside the original buying conversation should be able to follow that chain without guessing.
For a practical review, prepare the purchase order, final specification, supplier invoices, payment records, packing list, freight quotations and invoices, transport documents, customs entry, destination bills, receiving report, inspection evidence, credits, and claim status. Then bring the open questions, not just the total. That is where a cost-control review can still improve a decision.


[…] Related guide: landed-cost control guide for imports from China […]
[…] delivery, connect the decision record with actual invoices, receiving dates and discrepancies. The landed-cost control guide explains that later reconciliation. Here, ask the narrower learning question: which assumption […]