Design and verify cargo insurance around the goods, route, packing, risk transfer and claim evidence instead of relying on a certificate label.
Cargo insurance for imports from China: the short answer
Cargo insurance transfers selected physical-loss risks from the buyer or seller to an insurer for an agreed transit, subject to the policy wording, exclusions, deductible, insured value and claims duties. It is not a guarantee that a supplier will perform, that a carrier will deliver on time, or that every kind of damage will be paid. A useful policy begins with a precise route and cargo description, identifies who bears risk under the sales contract, names the insured party, covers the full intended transit, and states the clauses and extensions instead of relying on the phrase “all risks.”
For a shipment from China, decide the insurance arrangement before the purchase order is released. Match the policy to the goods, packaging, sea/air/road legs, transshipment, temporary storage and destination. Confirm the sum insured, currency, deductible, exclusions, war and strikes position, claim-notification route and evidence requirements in writing. When goods arrive, inspect before clean acceptance; if damage is found, protect the goods, notify the insurer and carrier promptly, preserve packaging and seals, and collect survey, transport, commercial and photographic evidence.
What cargo insurance does—and what it does not do
International procurement contains several different risks that are often bundled together in conversation. Supplier fraud, non-conforming goods, production delay, physical damage in transit, customs detention and currency loss are not the same problem. Cargo insurance is principally a contract for specified loss of or damage to an insured interest during the covered transit. The operative policy, certificate, schedule, endorsements and incorporated clauses determine the answer; a quotation email or a freight forwarder’s informal assurance does not.
Insurance can be valuable even when a carrier may be liable. Carrier liability is a separate legal route, may depend on the transport convention and contract, can have monetary limits and defences, and usually requires proof and timely notice. ICAO’s current Montreal Convention material, for example, records a revised cargo liability limit of 26 Special Drawing Rights per kilogram effective 28 December 2024 for covered international air carriage. That figure is not the value of the goods and it is not a promise that every air claim will reach that limit. A high-value, low-weight shipment can therefore expose a gap between the cargo value and a carrier-liability recovery.
Cargo insurance also does not repair a weak purchase contract. If the factory ships the wrong model, changes material without approval or misses the delivery date, the event may be a commercial or quality dispute rather than insured transit damage. Link the insurance work to the purchase specification, acceptance method and payment plan. Buyers who still need to organize the wider process can start with the China purchasing and import guides and the guide on how to start importing from China.
Four questions that prevent false confidence
- What event caused the loss? Fire, collision, theft, wetting, breakage, temperature variation, poor packing, delay and inherent vice may receive different treatment.
- When and where did it occur? Coverage attaches and terminates under the transit wording; storage, deviation and a changed destination require attention.
- Whose financial interest was exposed? The named insured, assignee or person claiming must have the relevant insured interest and documents.
- Which exact wording applies? Clause name, edition date, endorsements, exclusions and deductible matter more than a marketing label.
Build a shipment risk map before asking for a premium
A broker or insurer cannot design suitable cover from “one container from China” alone. IUMI’s guide identifies practical underwriting information such as the business profile, goods, inner and outer packing, annual values, countries, transport form, conveyances and Incoterms. Prepare one shipment sheet that is consistent with the purchase order, booking and policy request.
| Field | What to record | Why it matters |
|---|---|---|
| Goods | Exact product, material, model, use, fragility, dangerous or temperature-sensitive characteristics | Changes risk, exclusions, packing and underwriting questions |
| Value | Invoice, freight, insurance, other agreed costs and currency | Sets the basis for the sum insured and underinsurance review |
| Packing | Inner protection, carton/crate, pallet, moisture control, blocking, sealing and marks | Insufficient packing and inherent characteristics can defeat a claim |
| Route | Factory pickup, origin warehouse, port/airport, transshipment, destination terminal, final delivery | Tests whether every leg and storage period is within transit |
| Mode | Sea FCL/LCL, air, rail, road or courier and container/equipment type | Changes handling, aggregation and liability exposures |
| Parties | Seller, buyer, forwarder, carrier, warehouse, consignee and policyholder | Clarifies notices, documents and the party entitled to claim |
| Trade term | Incoterms rule, version and precise named place/port | Shows risk handoff and any seller insurance obligation |
| Loss history | Prior shortages, wetting, breakage, theft, temperature or handling events | Supports honest disclosure and targeted prevention |
Do not conceal awkward details to obtain a cheaper quote. Material-information duties depend on the governing law and policy, but incomplete or inaccurate disclosure can jeopardize cover. Record the questions asked, the answers supplied and the final underwriter acceptance. If the supplier controls packing or booking, obtain evidence from the actual factory rather than copying a generic statement from a platform listing. Use a separate process to verify a Chinese supplier and confirm the factory, seller and bank beneficiary.
Institute Cargo Clauses A, B and C: scope is not the alphabet
The Institute Cargo Clauses published through the International Underwriting Association are widely used reference wordings, but the policy must actually incorporate the relevant clause and edition. Clause A is commonly described as broad “all risks” cover for loss or damage to the insured subject matter, subject to exclusions. “All risks” does not mean every loss. The insured still has to show accidental physical loss or damage within the insured transit, and exclusions, deductible and conditions remain effective.
Clauses B and C are named-perils forms. They respond only when the loss falls within a listed peril, again subject to exclusions and policy terms. Clause C is narrower; Clause B includes additional listed causes compared with C. The practical buying question is not “Which letter sounds best?” It is “Which physical events could realistically damage these goods, and does the proposed wording respond to each one?”
| Decision area | Clause A approach | Clause B/C approach |
|---|---|---|
| Trigger | Broad accidental physical loss/damage, subject to exclusions | Claim must fit a listed insured peril |
| Best use of review | Study exclusions, deductibles and special cargo endorsements | Map each credible loss scenario to an expressly listed peril |
| Typical misunderstanding | Assuming delay, poor packing or inherent vice is covered because the words “all risks” appear | Assuming any transit damage is enough without proving the named cause |
| Evidence focus | Physical event, timing, extent and excluded-cause analysis | The same evidence plus clear proof of the listed peril |
Exclusions deserve a line-by-line review
Common Institute wording addresses deliberate misconduct, ordinary leakage or ordinary loss in weight or volume, ordinary wear, insufficient or unsuitable packing in defined circumstances, inherent vice, delay, certain insolvency/default situations, nuclear risks and unseaworthiness or unfitness in specified conditions. War and strikes are handled through separate clauses or endorsements rather than assumed to be included. Cyber, sanctions, temperature, mechanical or electrical derangement, theft from unattended vehicles and other risks may also be modified by policy language.
Create an exclusions matrix with four columns: wording, plain-language effect, relevance to the product and control/extension. For electronics, consider moisture, impact, theft and electrical derangement. For machinery, consider lifting, rust, dismantling and replacement of damaged parts. For food or chemicals, consider temperature records, contamination, shelf life and dangerous-goods compliance. Do not rely on a generic answer; obtain the full policy wording and any endorsement that changes it.
Incoterms: risk transfer is not the same as insurance quality
Incoterms rules allocate defined delivery, cost and risk obligations between seller and buyer; they do not replace the sales contract, transfer title or guarantee suitable insurance. ICC states that Incoterms 2020 uses different default insurance levels for CIF and CIP: CIF, for sea and inland-waterway trade, retains Institute Cargo Clauses C or similar minimum cover, while CIP requires the higher Clause A or similar level. The parties can agree different or additional insurance, but that agreement must be explicit.
Under many other Incoterms rules there is no rule-based obligation on one party to insure for the other. A buyer using EXW, FCA, FOB, CFR, CPT, DAP or another rule should not infer insurance from the freight arrangement. Identify the point of risk transfer, then ensure the buyer’s or seller’s policy attaches no later than that point and continues through the intended destination. Write the rule as, for example, “FCA [precise named place], Incoterms 2020,” not simply “FOB China.”
Verify seller-arranged insurance under CIF or CIP
- Policy/certificate issuer, authenticity and authority to issue.
- Named insured, party entitled to claim and any endorsement/assignment process.
- Goods, voyage, mode, departure, destination and dates.
- Clause and edition, special conditions, deductible, exclusions and additional war/strikes cover.
- Sum insured and currency compared with the contract and documentary-credit requirements.
- Claims agent or survey contact at destination and notice deadlines.
If a documentary credit is used, check its insurance-document conditions before shipment. ICC UCP 600 Article 28 addresses policies, certificates or declarations under open cover, issuer/signature, originals, timing, currency and coverage amount. A document that satisfies a bank presentation is not automatically proof that the operational risk is well covered, so documentary compliance and substantive coverage both need review.
Set the insured value, currency and deductible deliberately
The sum insured should follow the policy basis and commercial agreement, not a guessed rounded number. Depending on wording and governing practice, the calculation may begin with invoice value and include freight, insurance and an agreed uplift or other costs. The UK Marine Insurance Act’s goods valuation provision is one legal reference that includes prime cost plus shipping-related expenses and insurance charges, but a buyer must use the actual policy and applicable law. ICC materials commonly reference 110% in CIF/CIP or documentary-credit contexts; that percentage is not a universal substitute for reading the contract.
Underinsurance can reduce recovery or leave uninsured expenses. Overstating value does not create a profit entitlement and may create questions. Match the policy currency to the commercial exposure where possible and define how exchange rates will be established at loss. For machinery, ask how partial-loss replacement, freight for replacement parts, duties, labour, debris removal and expediting costs are treated. For used goods, samples or own-manufactured goods, agree the valuation basis in advance.
Understand the deductible
A deductible may apply per occurrence, per shipment, per package or by loss type. A percentage deductible might be calculated against the whole shipment or the damaged item, depending on wording. Model at least three loss sizes. If a USD 2,000 deductible makes the most likely carton-damage claims uneconomic, improve packing and decide whether insurance is intended mainly for severe losses. Do not split one occurrence artificially; ask how aggregation is handled for several containers affected by one event.
Single shipment, open cover or stock throughput
A one-off importer may use a voyage policy or certificate. A recurring importer can discuss open cover, where declarations are made under agreed annual terms, or a stock-throughput structure covering movement and storage across a broader chain. The operational advantage is consistency, but only if declarations, turnover estimates, maximum values, locations and reporting are accurate. Put ownership of declarations in one role and reconcile every shipment against the purchase and logistics register.
Packing is a coverage issue, not merely a supplier task
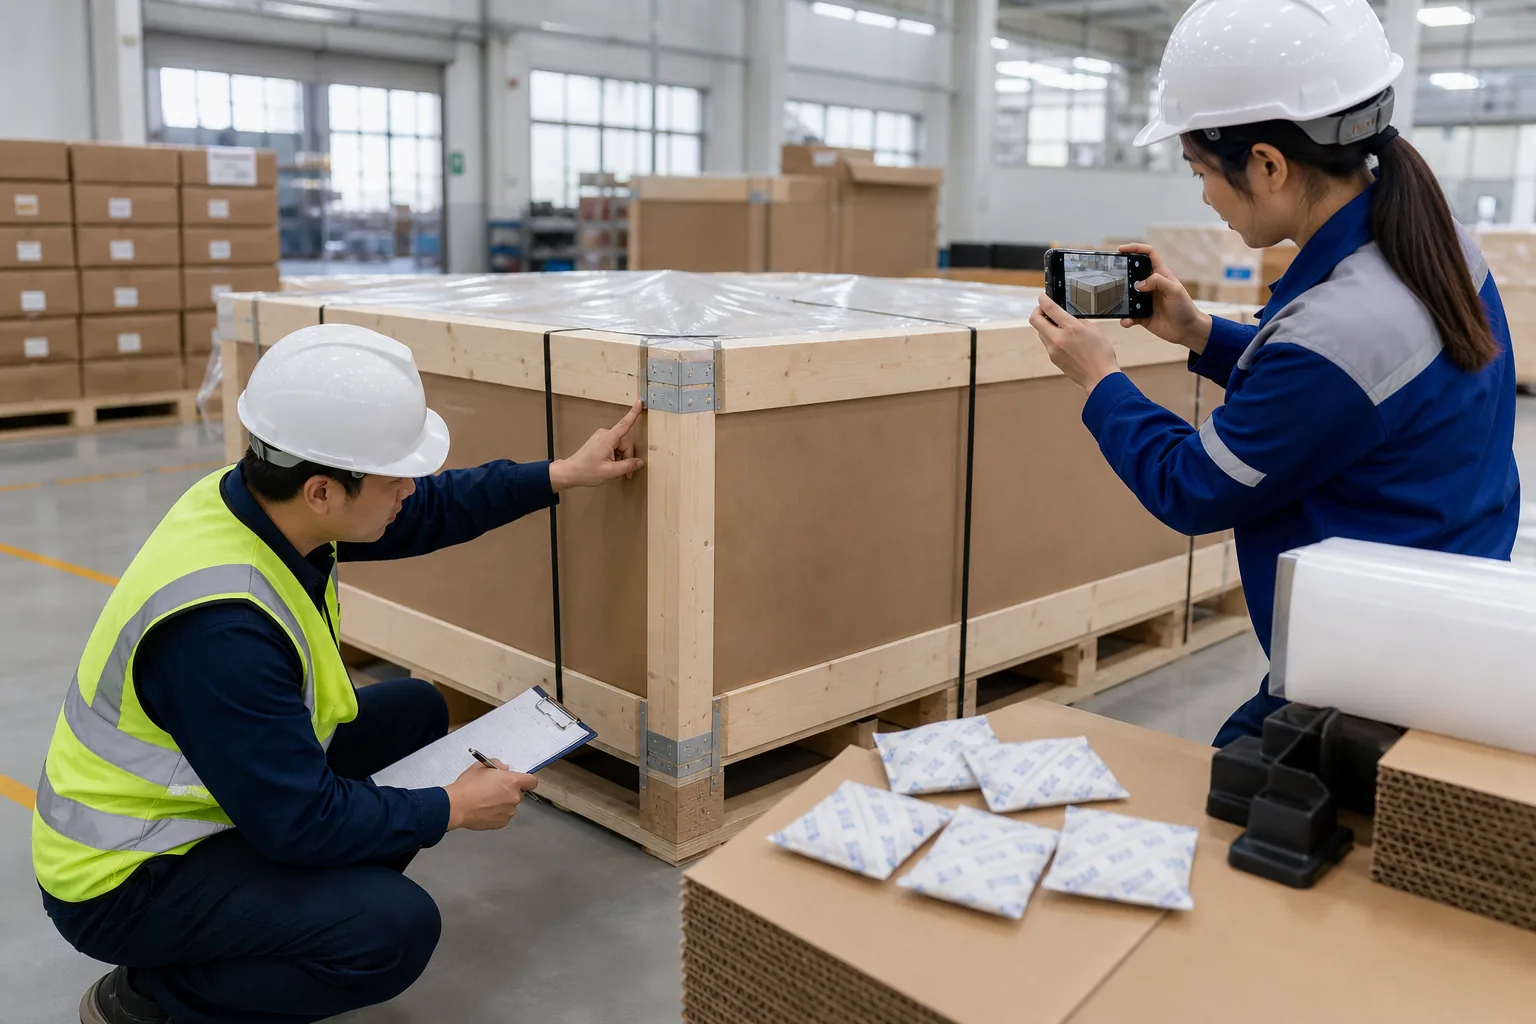
The joint IMO/ILO/UNECE CTU Code is a non-mandatory global code of practice for packing cargo transport units. It illustrates why cargo safety depends on selection of the unit, weight distribution, securing, moisture management, inspection and a documented chain of responsibility. Insurance cannot turn unsuitable packaging into good packaging. Institute exclusions may address insufficient or unsuitable packing in defined circumstances, and causation will matter.
Write packing requirements into the purchase specification: inner protection, material grade, carton strength, pallet dimensions, crate construction, corrosion barrier, desiccant calculation, blocking and bracing, shock/tilt indicators where appropriate, marks and maximum stacking. Require approval of a packing prototype for high-risk goods. At pre-shipment inspection, verify the actual production packing—not a staged sample—and record photos before closing, pallet pattern, seal number, package count and gross/net weight.
For LCL, expect more handling and coexistence with other cargo. For FCL, control container condition, dryness, odour, holes, floor and door seals before loading. For air freight, examine palletization, fragile-item protection and security-screening handling. If buying through Alibaba or 1688, the platform transaction does not replace a product-specific export packing specification.
Independent inspection and quality control can collect evidence, but the inspection scope must explicitly include packaging, markings, quantities and container loading. A report that only tests product function may not answer the insurer’s later questions about how water, impact or shortage occurred.
Match cover to sea, air and inland legs
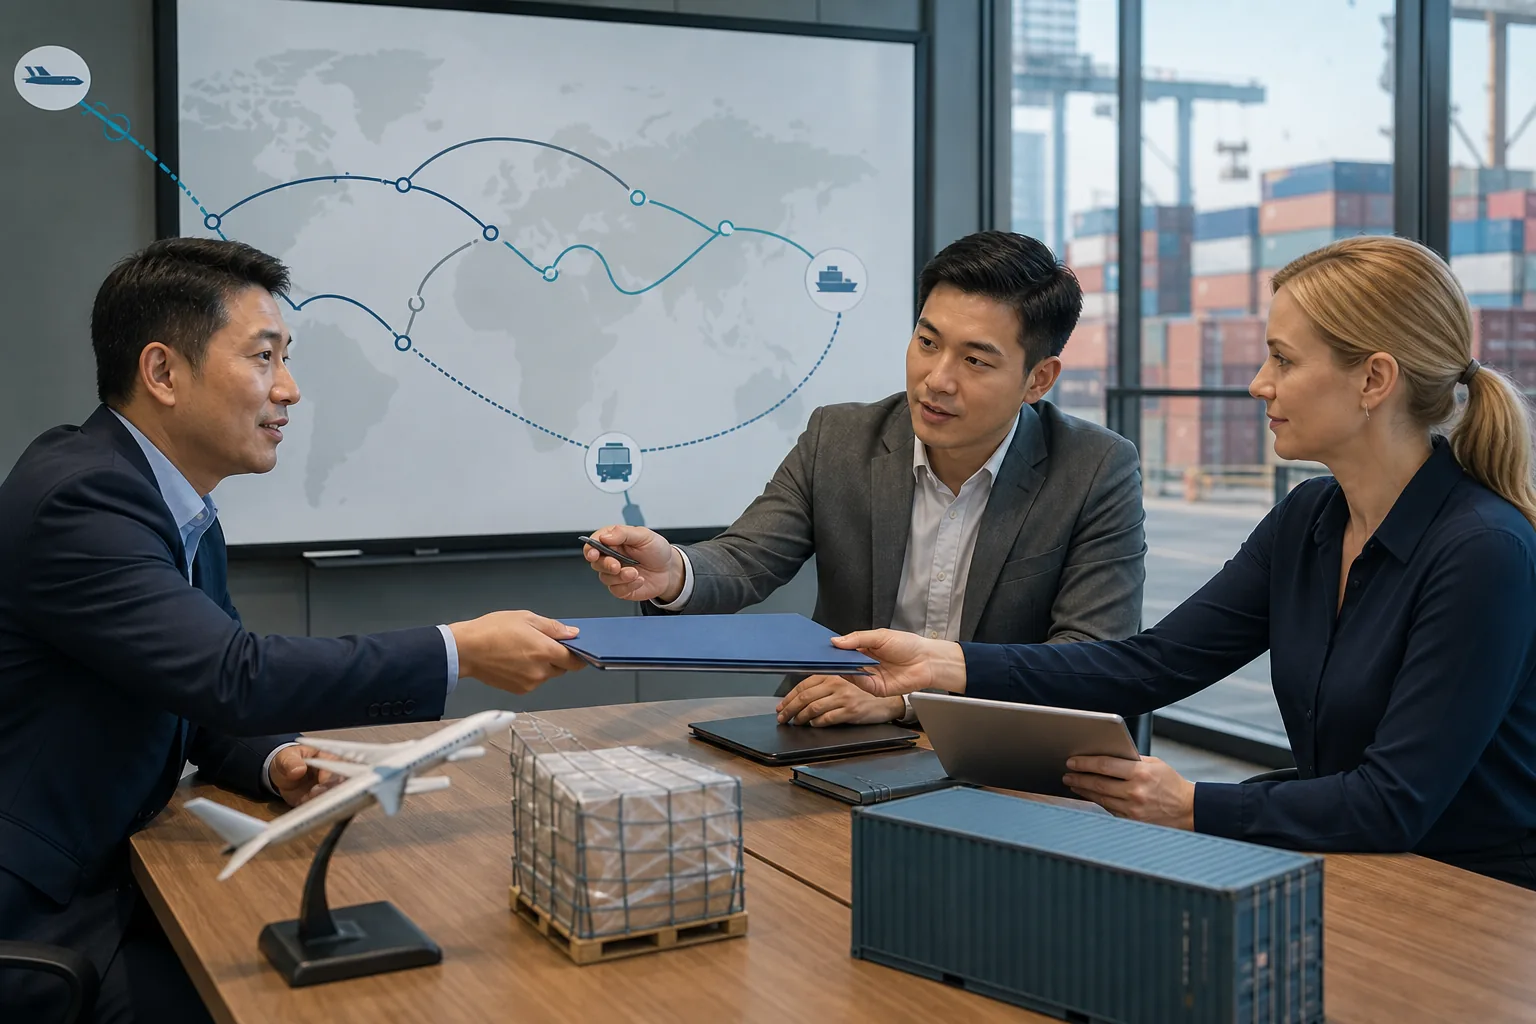
A China import rarely consists of one uninterrupted carrier movement. Factory pickup can precede consolidation, export warehousing, terminal handling, main carriage, transshipment, destination storage, customs examination and final trucking. Ask for warehouse-to-warehouse wording only after confirming what the wording actually treats as commencement, ordinary course of transit, storage and termination. A delay caused by the buyer after arrival may terminate or narrow cover even if the goods have not reached the buyer’s building.
Sea freight
Map wet damage, condensation, rough handling, container loss, fire, collision, grounding, general average and salvage exposure. General average can require cargo interests to provide security before release; verify how the policy treats contribution and security. For high-value cargo, check conveyance/classification requirements and maximum value per vessel or location. The IUMI guide highlights vessel-classification information and prompt notice issues in relevant clauses. Route changes and older or unsuitable vessels can require referral rather than silence.
Air freight
Air transit is faster but not damage-free. Multiple handling points, screening, pallet breakdown, theft and temperature excursions can matter. Compare the cargo value per kilogram with potential carrier-liability limits and confirm declared-value options separately from insurance. High-value electronics, precision instruments and pharmaceuticals may need specific security, temperature or concealed-damage procedures. Do not assume a courier’s advertised liability is cargo insurance.
Road, rail and multimodal transit
Carrier liability and notice rules can change by country, convention and document. The CMR convention, where applicable, addresses road-carriage documents, carrier responsibility, packing and written reservations; its scope is not universal for every China-to-destination movement. The practical response is a route-leg table showing carrier, document, liability regime to be checked, insured transit status and notice contact. Ask the broker to confirm that transshipment and ordinary incidental storage are not accidental gaps.
Use the operational comparison in choosing air or sea freight, but make the mode choice and the insurance choice separately. Faster transport can reduce exposure time while creating a high value concentration; cheaper transport may involve more storage or handling. Neither mode determines the right clause by itself.
Documents to verify before the goods leave China
Create one digital shipment file. It should allow a person who did not arrange the order to understand the insured interest, cargo, value, route, packing and handoffs. Preserve original files and message headers rather than screenshots alone.
- Sales evidence: signed purchase order or contract, specifications, approved sample reference, commercial invoice and payment records.
- Packing evidence: packing list, dimensions/weights, material and method, inspection report, loading photos and container seal.
- Transport evidence: booking, bill of lading, sea waybill, air waybill, rail/road document, forwarder receipt and tracking events.
- Insurance evidence: policy or certificate, schedule, full clauses, endorsements, exclusions, deductible, sum insured, currency and claims contacts.
- Compliance evidence: dangerous-goods declaration, temperature instruction, permits or product documents where applicable.
- Party evidence: seller, manufacturer, exporter, policyholder, insured, consignee, bank beneficiary and authorized contacts.
Check consistency. Product description, package count, weights, voyage, insured value and parties should not contradict each other without an explained amendment. Verify the policy reference directly with the insurer or authorized intermediary using independently obtained contact details. A polished PDF received from the supplier is data, not authentication.
When the factory, exporter and seller differ, record why. Supplier and factory verification can establish the parties, while product sourcing support can organize the commercial file; neither service should be presented as insurer approval.
Cargo damage on arrival: protect evidence in the first hours
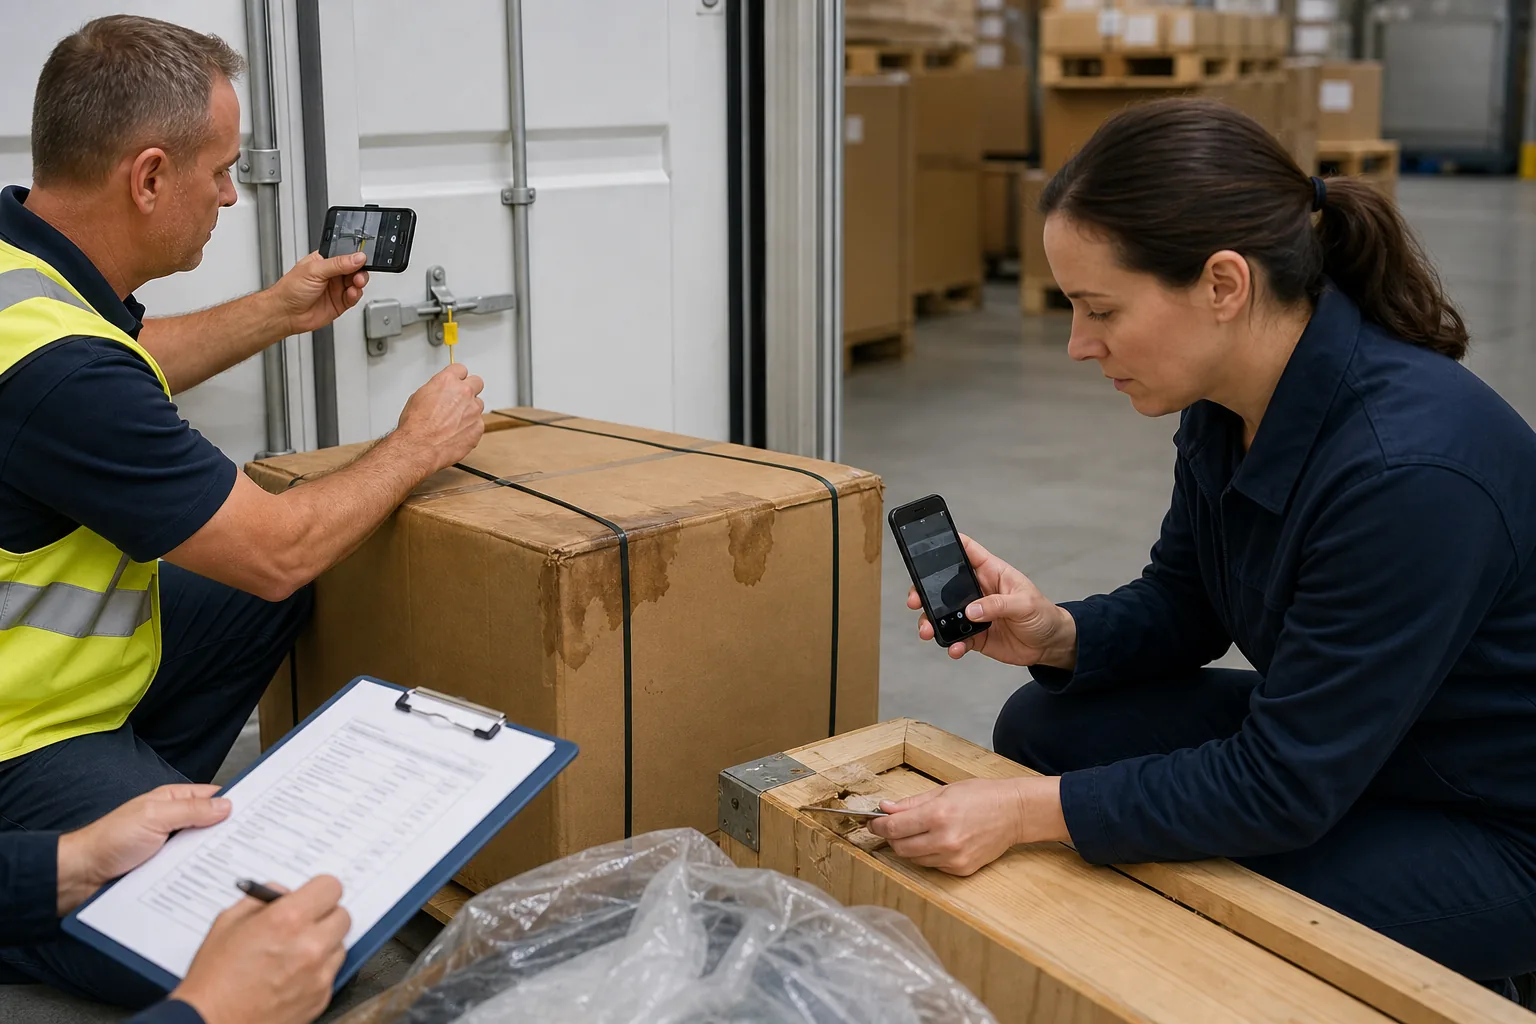
Claims are often weakened at delivery, before anyone reads the policy. Train the receiving team in advance. If a container, pallet or carton shows damage, do not sign an unqualified clean receipt merely to release the driver. Record reservations in the carrier’s system or document, subject to local rules and safety. Photograph the vehicle/container exterior, doors, seal before removal, opening sequence, stow, wet lines, packaging and goods. Keep timestamps and original files.
- Prevent further loss. Move goods to a safe area, separate wet from dry cargo, protect from weather and follow insurer instructions. Reasonable mitigation does not mean destroying evidence.
- Notify promptly. Contact the insurer/broker and the listed survey agent; notify the carrier, forwarder and other potentially responsible parties in writing. Policy and transport deadlines can be short.
- Preserve rights. State that loss/damage is being investigated and reserve recovery rights. Do not give a broad release or discard packaging.
- Arrange survey. Follow the policy on survey authority. Invite relevant parties when appropriate and retain damaged goods until disposal or salvage is authorized.
- Quantify carefully. Count affected units, test a defensible sample, separate repairable/saleable/total-loss goods and document valuation.
- Build the claim file. Policy/certificate, invoices, packing list, transport documents, notices, delivery record, survey, photos, repair/replacement quotations and mitigation expenses.
Visible and concealed damage
Apparent damage should be recorded at delivery. Concealed damage requires rapid internal inspection and written notice under the applicable transport and policy framework. Do not invent a universal deadline: the contract, convention, jurisdiction and policy differ. The receiving SOP should contain mode-specific contacts and deadlines verified for the actual shipment.
Do not repair, sell or dispose too early
An insurer may need to inspect, evaluate salvage or pursue a carrier. Emergency measures to prevent further loss may be necessary, but document the before-state and seek instructions. Keep samples and serial/batch references. If goods are unsafe, involve the competent safety or regulatory authority and prioritize people and environment over claim preservation.
Three practical China-import examples
Example 1: machinery arrives with rust inside an intact container
The buyer should not jump directly to “seawater damage.” Inspect container condition, moisture paths, packing barrier, desiccants, pre-loading state, transit duration and survey findings. Clause scope, insufficient-packing and inherent-vice issues may be argued. The preventive file should have factory photos of clean/dry machinery, sealed moisture barrier and loading. The claim file should preserve humidity/wet evidence, packaging and professional findings. A conclusion based only on orange surface color is weak.
Example 2: high-value electronics disappear during air handling
Confirm package count and weight at each handoff, security seals, tracking events, CCTV requests and exception records. Notify airline/forwarder and insurer immediately. Compare cargo value with the applicable carrier-liability framework and any special declaration. Review theft conditions, unattended-vehicle/security warranties and deductible. Do not assume the air waybill value equals the insured value.
Example 3: LCL cartons are crushed and several units fail
Document external compression, pallet/stack pattern, carton strength, internal protection and coexistence with heavier cargo. Determine whether damage arose from an insured handling event or inadequate packaging. Test a reasoned sample, keep failed units, quantify repair or replacement, and preserve evidence against consolidator and carriers. For future shipments, improve carton/crate specifications and consider whether FCL or a different consolidation plan changes the risk economically.
Pre-shipment cargo insurance decision checklist
- The legal seller, manufacturer, exporter, buyer, consignee and insured party are identified.
- The Incoterms rule includes the version and precise named place or port.
- Risk-transfer point and insurance attachment point have no unintended gap.
- The full factory-to-destination route, modes, transshipments and storage are declared.
- Goods and special characteristics are described accurately.
- Packing requirements and loading evidence are approved.
- Clause, edition, endorsements, exclusions, war/strikes position and deductible are received.
- Sum insured, valuation basis and currency match the commercial exposure.
- Maximum values per conveyance/location and declaration duties are workable.
- The certificate/policy is authenticated through an independent channel.
- Destination survey and claims contacts are known to the receiving team.
- Carrier notice and insurance notice procedures are written into the receiving SOP.
- Original commercial, packing, transport, insurance and inspection records are preserved.
This checklist is an operational review, not a policy interpretation or legal opinion. Coverage depends on the issued contract and applicable law. Obtain an insurance professional’s written advice for the actual cargo and route, and legal advice for disputed wording or recovery rights.
Frequently asked questions
Is cargo insurance mandatory for imports from China?
Not universally. A sales contract, Incoterms rule, financing arrangement, domestic law or risk policy may create a requirement. Even when not mandatory, compare the uninsured exposure with the policy cost and exclusions.
Does CIF mean the buyer has broad all-risks insurance?
No. ICC explains that CIF’s default insurance level under Incoterms 2020 is Clause C or similar minimum cover, unless the parties agree otherwise. Verify the actual certificate and wording.
Is Clause A really all risks?
It is broad accidental physical loss/damage cover subject to exclusions, conditions and deductible. Delay, ordinary wear, inherent vice and defined packing problems are examples of matters that can remain outside cover.
Should the buyer insure invoice value or 110%?
Use the policy valuation basis and contract. The 110% convention appears in particular Incoterms/documentary contexts, but it is not a universal rule for every policy or every recoverable expense.
Who files the claim when the supplier arranged insurance?
The certificate, policy, assignment and insured-interest position determine who can claim. Confirm this before payment and shipment, including how originals or electronic documents will be transferred.
Can the freight forwarder’s liability replace cargo insurance?
Usually they are different protections. Forwarder/carrier liability depends on fault, contract, convention, limits and defences; cargo insurance responds under its own wording and may pursue recovery afterward.
Authoritative sources reviewed
- International Union of Marine Insurance — Guide to Marine Cargo Insurance
- International Underwriting Association — Institute CL Clauses index
- International Chamber of Commerce — Incoterms 2020
- International Chamber of Commerce — UCP 600, Article 28
- ICAO — Montreal Convention status and revised liability limits
- UNECE/IMO/ILO — Code of Practice for Packing Cargo Transport Units
- UK legislation — Marine Insurance Act 1906
- UNIDROIT — CMR 1956 convention text
Sources were accessed on 25 August 2026. Policy language, sanctions, routes, liability limits and local legal requirements can change; recheck them for the specific shipment.
[…] Related guide: cargo-insurance guide for imports from China […]
[…] cargo insurance guide explains why evidence and notification matter, but a complete loading file does not guarantee […]
[…] risk and insurance questions separate. Our cargo insurance guide for imports from China explains the broader insurance review. A policy should not be treated as a substitute for packing […]